Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
Contingency expenses, exempt-income disallowance, and royalty benchmarking: unsupported adjustments were deleted under consistent accounting and trans...
Page of 4921
Press 'Enter' after typing page number.
81 to 100 of 98414 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
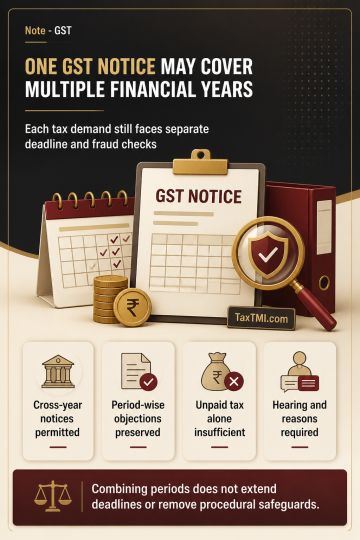
Sections 73 and 74 of the CGST Act permit a common show cause notice covering multiple tax periods or financial years, as the expressions "for any period" and "such periods" do not impose a financial-year-specific bar. Financial-year references in the order-limitation provisions operate as separate limitation benchmarks for each demand component; consolidation cannot extend limitation or defeat period-wise objections. Section 74 requires disclosed material supporting fraud, wilful misstatement or suppression of facts to evade tax, and cannot be invoked merely because tax remains unpaid. Rule 142 and FORM GST DRC-01 regulate electronic notice communication without restricting consolidation. Notice-specific allegations, quantified demands, hearing rights, reasoned orders and limits on confirmation remain applicable.
Sections 73 and 74 of the CGST Act permit a common show cause notice covering multiple tax periods or financial years, as the expressions "for any period" and "such periods" do not impose a financial-year-specific bar. Financial-year references in the order-limitation provisions operate as separate limitation benchmarks for each demand component; consolidation cannot extend limitation or defeat period-wise objections. Section 74 requires disclosed material supporting fraud, wilful misstatement or suppression of facts to evade tax, and cannot be invoked merely because tax remains unpaid. Rule 142 and FORM GST DRC-01 regulate electronic notice communication without restricting consolidation. Notice-specific allegations, quantified demands, hearing rights, reasoned orders and limits on confirmation remain applicable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921