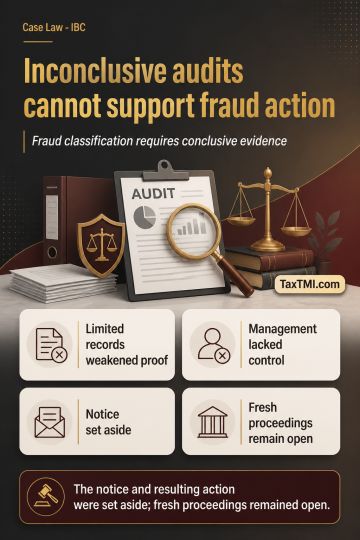
Fraud classification show-cause notices founded on inconclusive forensic audit material cannot sustain action, permitting fresh proceedings on conclus...
Appellate enhancement limits protect against new income sources, while documented credits and prior-year investments resist unexplained-income additio...
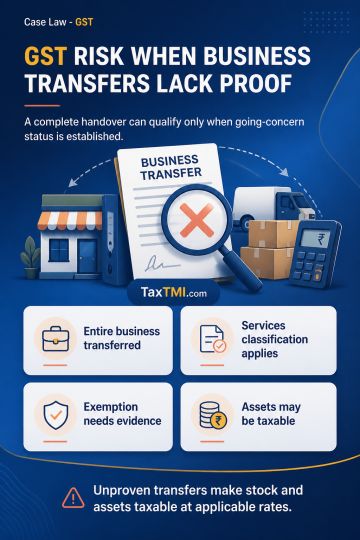
Under GST, a comprehensive transfer of an entire proprietorship business to an LLP without consideration, including assets, liabilities, employees and business rights, constitutes a supply even if not made in the ordinary course of business. Transfer of a business as a going concern is classified as a supply of services because it is excluded from treatment as a supply of goods. The going-concern exemption applies only where the business is established as a going concern under applicable standards. If that status is not established, transferred stock and other business assets are treated as taxable supplies of goods at the applicable rates.
Under GST, a comprehensive transfer of an entire proprietorship business to an LLP without consideration, including assets, liabilities, employees and business rights, constitutes a supply even if not made in the ordinary course of business. Transfer of a business as a going concern is classified as a supply of services because it is excluded from treatment as a supply of goods. The going-concern exemption applies only where the business is established as a going concern under applicable standards. If that status is not established, transferred stock and other business assets are treated as taxable supplies of goods at the applicable rates.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4936