Request-driven road restoration attracts reverse-charge GST, not governmental-function treatment or compensatory-damages status for business recipient...
Road restoration charges for commercial pipeline works are taxable Government services, with reverse charge liability and no public-function exemption...
Model-wise import cap monitoring cannot justify withholding used multifunction machines where all-India tracking is absent and full security is furnis...
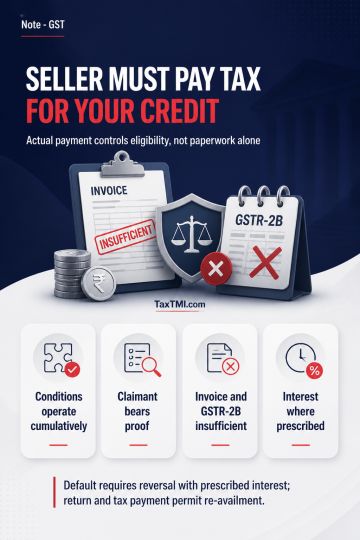
Input tax credit under the CGST Act is conditional on the supplier's actual payment of tax to the Government; invoice possession, receipt of supplies and GSTR-2B reflection do not independently establish final eligibility. Section 16(2) conditions operate cumulatively, with the claimant bearing the burden of proving eligibility. Under Section 41(2) and Rule 37A, credit attributable to supplier non-payment must be reversed with applicable interest where prescribed, but may be re-availed when the supplier furnishes the relevant return and pays tax. The condition is treated as substantive, not as unconstitutional deprivation or double taxation, and cannot be read down to exempt bona fide recipients absent fraud or collusion.
Input tax credit under the CGST Act is conditional on the supplier's actual payment of tax to the Government; invoice possession, receipt of supplies and GSTR-2B reflection do not independently establish final eligibility. Section 16(2) conditions operate cumulatively, with the claimant bearing the burden of proving eligibility. Under Section 41(2) and Rule 37A, credit attributable to supplier non-payment must be reversed with applicable interest where prescribed, but may be re-availed when the supplier furnishes the relevant return and pays tax. The condition is treated as substantive, not as unconstitutional deprivation or double taxation, and cannot be read down to exempt bona fide recipients absent fraud or collusion.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918