Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
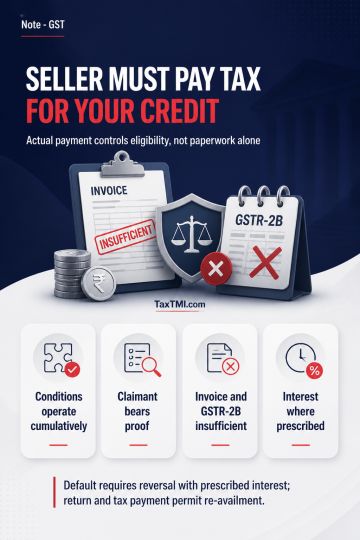
Input tax credit under the CGST Act is conditional on the supplier's actual payment of tax to the Government; invoice possession, receipt of supplies and GSTR-2B reflection do not independently establish final eligibility. Section 16(2) conditions operate cumulatively, with the claimant bearing the burden of proving eligibility. Under Section 41(2) and Rule 37A, credit attributable to supplier non-payment must be reversed with applicable interest where prescribed, but may be re-availed when the supplier furnishes the relevant return and pays tax. The condition is treated as substantive, not as unconstitutional deprivation or double taxation, and cannot be read down to exempt bona fide recipients absent fraud or collusion.
Input tax credit under the CGST Act is conditional on the supplier's actual payment of tax to the Government; invoice possession, receipt of supplies and GSTR-2B reflection do not independently establish final eligibility. Section 16(2) conditions operate cumulatively, with the claimant bearing the burden of proving eligibility. Under Section 41(2) and Rule 37A, credit attributable to supplier non-payment must be reversed with applicable interest where prescribed, but may be re-availed when the supplier furnishes the relevant return and pays tax. The condition is treated as substantive, not as unconstitutional deprivation or double taxation, and cannot be read down to exempt bona fide recipients absent fraud or collusion.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI