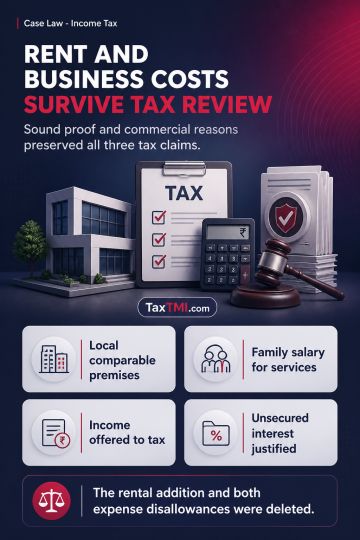
Rental income valuation requires credible local comparables; family-business salary and commercially expedient unsecured-loan interest remained deduct...
Strict construction of customs exemptions denied concession for brake components, while limitation restricted differential duty to timely Bills of Ent...
Way Leave Permissions cannot be retrospectively revived through insolvency plans, and affected infrastructure holders require safety review and hearin...
Parallel GST adjudication under Sections 73 and 74 for the same financial period was treated as incongruous once adjudication under Section 73 had concluded; the show cause notice, adjudication order and summary order under Section 74 were quashed. The ex parte Section 73 adjudication was also quashed and restored for fresh consideration because the taxpayer asserted that exemption documents and a reply could substantiate its position on the alleged mismatch or erroneous declaration. Reconsideration must occur after receiving the taxpayer's reply and supporting documents, while the merits of the exemption claim remain open.
Parallel GST adjudication under Sections 73 and 74 for the same financial period was treated as incongruous once adjudication under Section 73 had concluded; the show cause notice, adjudication order and summary order under Section 74 were quashed. The ex parte Section 73 adjudication was also quashed and restored for fresh consideration because the taxpayer asserted that exemption documents and a reply could substantiate its position on the alleged mismatch or erroneous declaration. Reconsideration must occur after receiving the taxpayer's reply and supporting documents, while the merits of the exemption claim remain open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915