Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
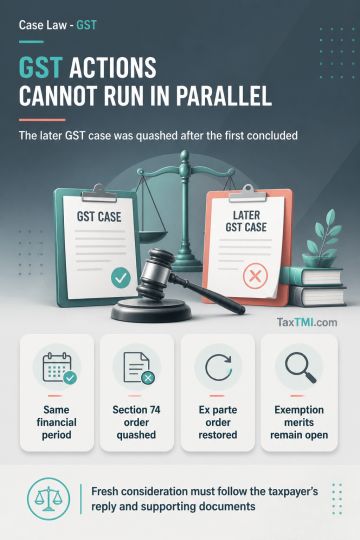
Parallel GST adjudication under Sections 73 and 74 for the same financial period was treated as incongruous once adjudication under Section 73 had concluded; the show cause notice, adjudication order and summary order under Section 74 were quashed. The ex parte Section 73 adjudication was also quashed and restored for fresh consideration because the taxpayer asserted that exemption documents and a reply could substantiate its position on the alleged mismatch or erroneous declaration. Reconsideration must occur after receiving the taxpayer's reply and supporting documents, while the merits of the exemption claim remain open.
Parallel GST adjudication under Sections 73 and 74 for the same financial period was treated as incongruous once adjudication under Section 73 had concluded; the show cause notice, adjudication order and summary order under Section 74 were quashed. The ex parte Section 73 adjudication was also quashed and restored for fresh consideration because the taxpayer asserted that exemption documents and a reply could substantiate its position on the alleged mismatch or erroneous declaration. Reconsideration must occur after receiving the taxpayer's reply and supporting documents, while the merits of the exemption claim remain open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915