Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
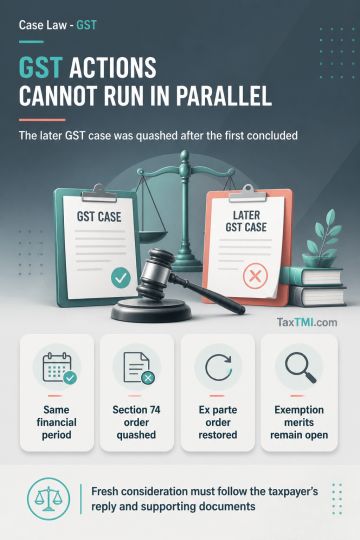
Parallel GST adjudication under Sections 73 and 74 for the same financial period was treated as incongruous once adjudication under Section 73 had concluded; the show cause notice, adjudication order and summary order under Section 74 were quashed. The ex parte Section 73 adjudication was also quashed and restored for fresh consideration because the taxpayer asserted that exemption documents and a reply could substantiate its position on the alleged mismatch or erroneous declaration. Reconsideration must occur after receiving the taxpayer's reply and supporting documents, while the merits of the exemption claim remain open.
Parallel GST adjudication under Sections 73 and 74 for the same financial period was treated as incongruous once adjudication under Section 73 had concluded; the show cause notice, adjudication order and summary order under Section 74 were quashed. The ex parte Section 73 adjudication was also quashed and restored for fresh consideration because the taxpayer asserted that exemption documents and a reply could substantiate its position on the alleged mismatch or erroneous declaration. Reconsideration must occur after receiving the taxpayer's reply and supporting documents, while the merits of the exemption claim remain open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI