Request-driven road restoration attracts reverse-charge GST, not governmental-function treatment or compensatory-damages status for business recipient...
Road restoration charges for commercial pipeline works are taxable Government services, with reverse charge liability and no public-function exemption...
Model-wise import cap monitoring cannot justify withholding used multifunction machines where all-India tracking is absent and full security is furnis...
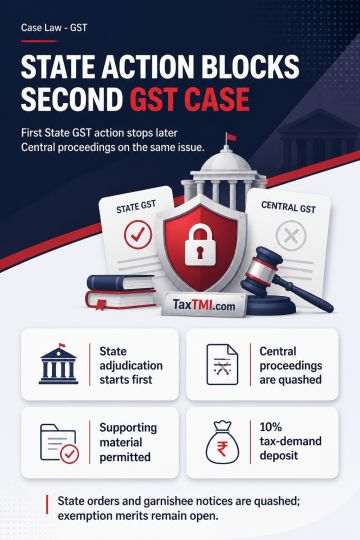
Section 6(2)(b) of the CGST Act bars a Central Tax proper officer from initiating proceedings on a subject matter already taken up by a State GST proper officer. Subsequent Central Tax show-cause and adjudication proceedings on the same matter were therefore quashed. For street-light works contracts, the claimed exemption depended on demonstrating that the value of goods supplied remained below the prescribed proportion of the contract value. State Tax adjudication orders and consequential garnishee notices were quashed to permit responses and supporting material, subject to deposit of 10% of the tax demand; the exemption merits remain open.
Section 6(2)(b) of the CGST Act bars a Central Tax proper officer from initiating proceedings on a subject matter already taken up by a State GST proper officer. Subsequent Central Tax show-cause and adjudication proceedings on the same matter were therefore quashed. For street-light works contracts, the claimed exemption depended on demonstrating that the value of goods supplied remained below the prescribed proportion of the contract value. State Tax adjudication orders and consequential garnishee notices were quashed to permit responses and supporting material, subject to deposit of 10% of the tax demand; the exemption merits remain open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916