Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
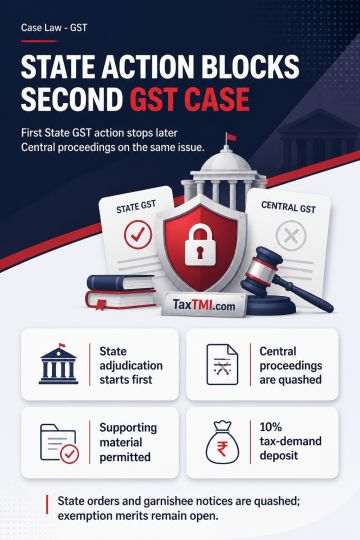
Section 6(2)(b) of the CGST Act bars a Central Tax proper officer from initiating proceedings on a subject matter already taken up by a State GST proper officer. Subsequent Central Tax show-cause and adjudication proceedings on the same matter were therefore quashed. For street-light works contracts, the claimed exemption depended on demonstrating that the value of goods supplied remained below the prescribed proportion of the contract value. State Tax adjudication orders and consequential garnishee notices were quashed to permit responses and supporting material, subject to deposit of 10% of the tax demand; the exemption merits remain open.
Section 6(2)(b) of the CGST Act bars a Central Tax proper officer from initiating proceedings on a subject matter already taken up by a State GST proper officer. Subsequent Central Tax show-cause and adjudication proceedings on the same matter were therefore quashed. For street-light works contracts, the claimed exemption depended on demonstrating that the value of goods supplied remained below the prescribed proportion of the contract value. State Tax adjudication orders and consequential garnishee notices were quashed to permit responses and supporting material, subject to deposit of 10% of the tax demand; the exemption merits remain open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915