Delayed judgment pronouncement alone does not invalidate Tribunal orders, while rectification cannot reopen evidence or negate confiscation-related pe...
Agricultural-land reinvestment qualifies when transfer consideration precedes replacement purchase, while unexamined claims may be reassessed on escap...
Bona fide public fixed-deposit explanations prevent concealment penalties where unexplained-credit additions lack independent evidence of undisclosed ...
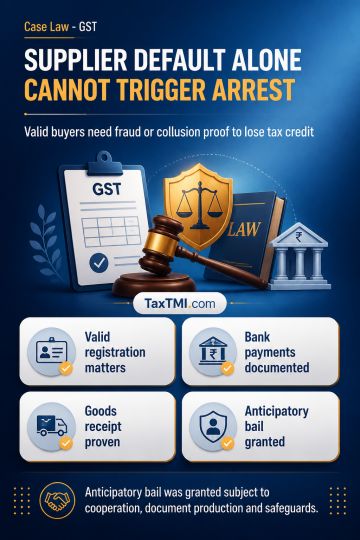
Input tax credit of a registered purchaser cannot ordinarily be denied merely because the supplier later becomes non-existent or defaults, where the purchaser holds valid registration, invoices, banking-channel payment evidence and filed returns, unless fraud or collusion is established. Documentary proof of actual receipt of goods and absence of prima facie collusion ordinarily make custodial interrogation unnecessary. Arrest for cognizable CGST offences requires the Commissioner's recorded reasons to believe, based on material satisfying statutory conditions rather than suspicion alone. Anticipatory bail in alleged wrongful input tax credit availment was granted subject to cooperation, document production and other safeguards.
Input tax credit of a registered purchaser cannot ordinarily be denied merely because the supplier later becomes non-existent or defaults, where the purchaser holds valid registration, invoices, banking-channel payment evidence and filed returns, unless fraud or collusion is established. Documentary proof of actual receipt of goods and absence of prima facie collusion ordinarily make custodial interrogation unnecessary. Arrest for cognizable CGST offences requires the Commissioner's recorded reasons to believe, based on material satisfying statutory conditions rather than suspicion alone. Anticipatory bail in alleged wrongful input tax credit availment was granted subject to cooperation, document production and other safeguards.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918