Concurrent anticipatory-bail jurisdiction permits applications before either forum, while secured evidence may negate custodial interrogation in GST e...
Transfer Pricing Officer jurisdiction is transaction-specific, excluding permanent establishment determinations and requiring independent assessment o...
Page of 4913
Press 'Enter' after typing page number.
1261 to 1280 of 98250 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
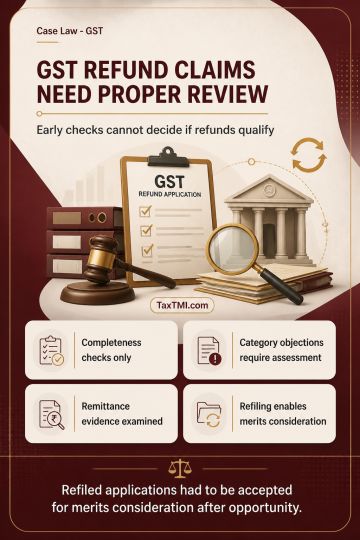
Rule 90(2) limits scrutiny of a GST refund application to its completeness under Rule 89(2), (3) and (4); it does not permit a deficiency memo to decide merits. Objections concerning the correct refund category, required statutory statements, adequacy of foreign-remittance evidence, or limitation require substantive examination by the competent authority. An Advice of Foreign Inward Remittance cannot be rejected solely by its label without assessing whether its contents meet the purpose of a Bank Realisation Certificate or FIRC. Deficiency memos on those grounds were unsustainable, and refiled applications had to be accepted for merits consideration after the applicable opportunity.
Rule 90(2) limits scrutiny of a GST refund application to its completeness under Rule 89(2), (3) and (4); it does not permit a deficiency memo to decide merits. Objections concerning the correct refund category, required statutory statements, adequacy of foreign-remittance evidence, or limitation require substantive examination by the competent authority. An Advice of Foreign Inward Remittance cannot be rejected solely by its label without assessing whether its contents meet the purpose of a Bank Realisation Certificate or FIRC. Deficiency memos on those grounds were unsustainable, and refiled applications had to be accepted for merits consideration after the applicable opportunity.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913