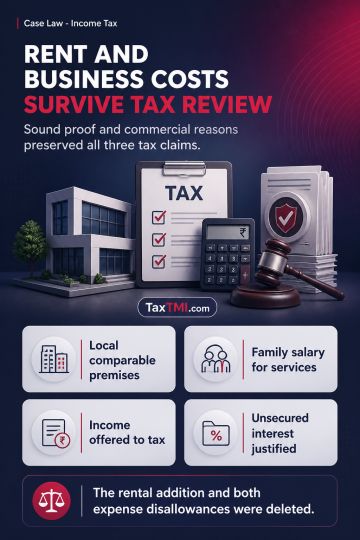
Rental income valuation requires credible local comparables; family-business salary and commercially expedient unsecured-loan interest remained deduct...
Strict construction of customs exemptions denied concession for brake components, while limitation restricted differential duty to timely Bills of Ent...
Page of 4913
Press 'Enter' after typing page number.
1281 to 1300 of 98250 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
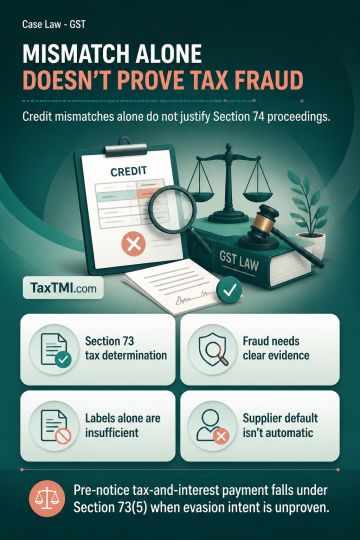
Input tax credit mismatches between Forms GSTR-3B and GSTR-2A may support tax determination under section 73, but do not by themselves justify section 74 proceedings or penalties. Section 74 requires clear evidence connecting wrongful credit availment with fraud, wilful misstatement, or suppression of facts intended to evade tax; merely reciting those terms is insufficient. Payment of tax and interest before notice, including after verification, falls within section 73(5) where no intent to evade is established. A supplier's default cannot automatically be attributed to the recipient as suppression.
Input tax credit mismatches between Forms GSTR-3B and GSTR-2A may support tax determination under section 73, but do not by themselves justify section 74 proceedings or penalties. Section 74 requires clear evidence connecting wrongful credit availment with fraud, wilful misstatement, or suppression of facts intended to evade tax; merely reciting those terms is insufficient. Payment of tax and interest before notice, including after verification, falls within section 73(5) where no intent to evade is established. A supplier's default cannot automatically be attributed to the recipient as suppression.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913