Request-driven road restoration attracts reverse-charge GST, not governmental-function treatment or compensatory-damages status for business recipient...
Road restoration charges for commercial pipeline works are taxable Government services, with reverse charge liability and no public-function exemption...
Model-wise import cap monitoring cannot justify withholding used multifunction machines where all-India tracking is absent and full security is furnis...
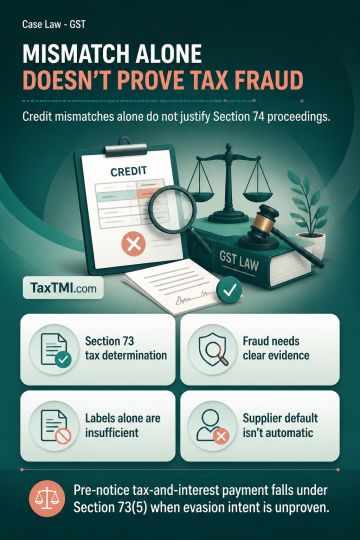
Input tax credit mismatches between Forms GSTR-3B and GSTR-2A may support tax determination under section 73, but do not by themselves justify section 74 proceedings or penalties. Section 74 requires clear evidence connecting wrongful credit availment with fraud, wilful misstatement, or suppression of facts intended to evade tax; merely reciting those terms is insufficient. Payment of tax and interest before notice, including after verification, falls within section 73(5) where no intent to evade is established. A supplier's default cannot automatically be attributed to the recipient as suppression.
Input tax credit mismatches between Forms GSTR-3B and GSTR-2A may support tax determination under section 73, but do not by themselves justify section 74 proceedings or penalties. Section 74 requires clear evidence connecting wrongful credit availment with fraud, wilful misstatement, or suppression of facts intended to evade tax; merely reciting those terms is insufficient. Payment of tax and interest before notice, including after verification, falls within section 73(5) where no intent to evade is established. A supplier's default cannot automatically be attributed to the recipient as suppression.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915