Concurrent anticipatory-bail jurisdiction permits applications before either forum, while secured evidence may negate custodial interrogation in GST e...
Transfer Pricing Officer jurisdiction is transaction-specific, excluding permanent establishment determinations and requiring independent assessment o...
Page of 4913
Press 'Enter' after typing page number.
1261 to 1280 of 98250 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
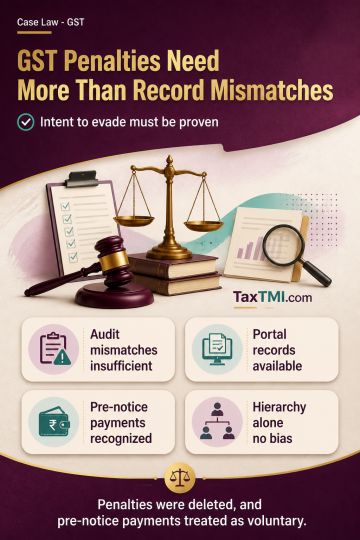
Section 74 penalties for excess input tax credit and irregular transitional credit require positive material proving fraud, wilful misstatement, or suppression with intent to evade tax; audit mismatches, record-based discrepancies, and mechanical allegations are insufficient. Where returns and credit declarations are available on the departmental portal and tax and interest are paid before a show cause notice without deliberate evasion, the payments fall within Section 73(5) read with Section 73(8). On those principles, the Section 74 penalties were deleted, and the pre-notice tax and interest payments were treated as voluntary payments. Departmental hierarchy alone also does not establish a real likelihood of institutional bias in statutory appellate proceedings.
Section 74 penalties for excess input tax credit and irregular transitional credit require positive material proving fraud, wilful misstatement, or suppression with intent to evade tax; audit mismatches, record-based discrepancies, and mechanical allegations are insufficient. Where returns and credit declarations are available on the departmental portal and tax and interest are paid before a show cause notice without deliberate evasion, the payments fall within Section 73(5) read with Section 73(8). On those principles, the Section 74 penalties were deleted, and the pre-notice tax and interest payments were treated as voluntary payments. Departmental hierarchy alone also does not establish a real likelihood of institutional bias in statutory appellate proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913