Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
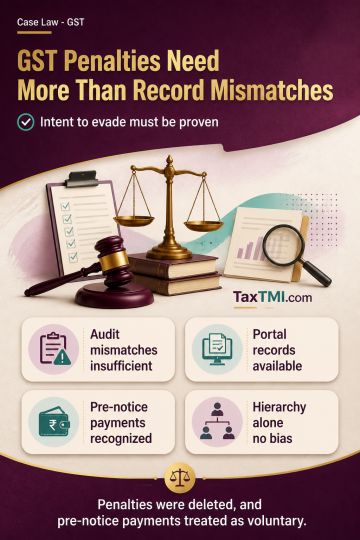
Section 74 penalties for excess input tax credit and irregular transitional credit require positive material proving fraud, wilful misstatement, or suppression with intent to evade tax; audit mismatches, record-based discrepancies, and mechanical allegations are insufficient. Where returns and credit declarations are available on the departmental portal and tax and interest are paid before a show cause notice without deliberate evasion, the payments fall within Section 73(5) read with Section 73(8). On those principles, the Section 74 penalties were deleted, and the pre-notice tax and interest payments were treated as voluntary payments. Departmental hierarchy alone also does not establish a real likelihood of institutional bias in statutory appellate proceedings.
Section 74 penalties for excess input tax credit and irregular transitional credit require positive material proving fraud, wilful misstatement, or suppression with intent to evade tax; audit mismatches, record-based discrepancies, and mechanical allegations are insufficient. Where returns and credit declarations are available on the departmental portal and tax and interest are paid before a show cause notice without deliberate evasion, the payments fall within Section 73(5) read with Section 73(8). On those principles, the Section 74 penalties were deleted, and the pre-notice tax and interest payments were treated as voluntary payments. Departmental hierarchy alone also does not establish a real likelihood of institutional bias in statutory appellate proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913