Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
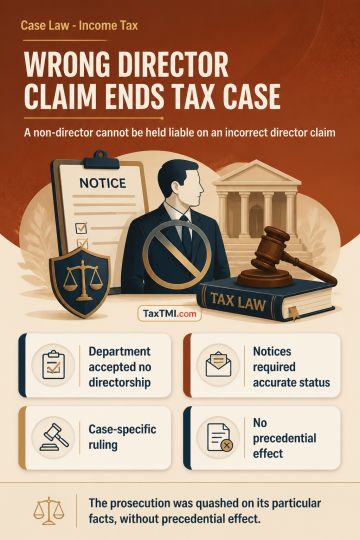
Wrongful treatment of an individual as a company's Principal Officer can undermine criminal prosecution for delayed deposit of tax deducted at source when the prosecution is founded on an incorrect assertion that the individual was a director. The show-cause notice, designation order, sanction and complaint must rest on accurate corporate status. Where the Department accepts that the accused was never a director, vicarious liability cannot be sustained on that premise; the prosecution was quashed on its particular facts without precedential effect.
Wrongful treatment of an individual as a company's Principal Officer can undermine criminal prosecution for delayed deposit of tax deducted at source when the prosecution is founded on an incorrect assertion that the individual was a director. The show-cause notice, designation order, sanction and complaint must rest on accurate corporate status. Where the Department accepts that the accused was never a director, vicarious liability cannot be sustained on that premise; the prosecution was quashed on its particular facts without precedential effect.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915