Anti-profiteering obligations survive business demerger, complaint withdrawal, and customized supply arrangements where rate-reduction benefits are no...
Road restoration charges constitute taxable services when requested for commercial pipeline activity, requiring reverse-charge GST from the business r...
Interest on delayed release of requisitioned cash includes statutory pre-assessment interest and restitutionary compensation for unlawful post-assessm...
Incomplete inventory records justify rejecting accounts, while profit estimation requires relevant comparable material and interest falls under other ...
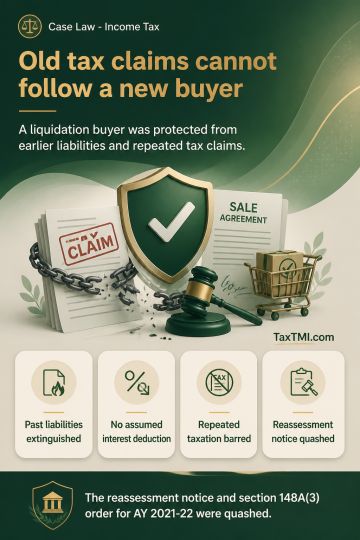
Clean-slate protection applies where a corporate debtor is sold as a going concern in liquidation: past liabilities and related investigations are extinguished, preventing an alleged past interest cessation from being imposed on the purchaser. Reassessment cannot rest on a presumption that unpaid interest was deducted when accounts and the taxpayer's reply showed otherwise. The same alleged cessation from one transaction cannot be taxed repeatedly across assessment years. Failure to address the clean-slate defence and binding precedents rendered the reassessment notice and section 148A(3) order for AY 2021-22 unsustainable and quashed.
Clean-slate protection applies where a corporate debtor is sold as a going concern in liquidation: past liabilities and related investigations are extinguished, preventing an alleged past interest cessation from being imposed on the purchaser. Reassessment cannot rest on a presumption that unpaid interest was deducted when accounts and the taxpayer's reply showed otherwise. The same alleged cessation from one transaction cannot be taxed repeatedly across assessment years. Failure to address the clean-slate defence and binding precedents rendered the reassessment notice and section 148A(3) order for AY 2021-22 unsustainable and quashed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916