Strict construction of customs exemptions denied concession for brake components, while limitation restricted differential duty to timely Bills of Ent...
Way Leave Permissions cannot be retrospectively revived through insolvency plans, and affected infrastructure holders require safety review and hearin...
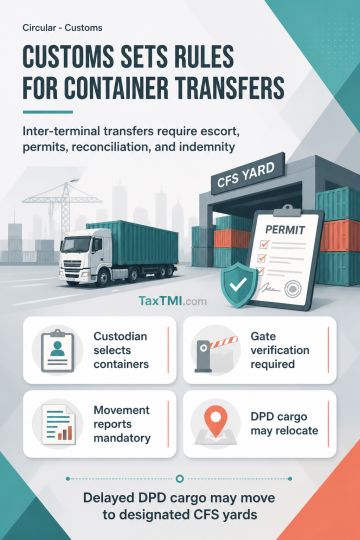
Inter-terminal container movement requires customs escort, permit reconciliation, and indemnity, while delayed DPD cargo may move to designated CFS ya...
Year-wise GST tax periods make composite show cause notices impermissible, requiring separate proceedings despite contrary non-jurisdictional preceden...
Page of 4918
Press 'Enter' after typing page number.
1401 to 1420 of 98352 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
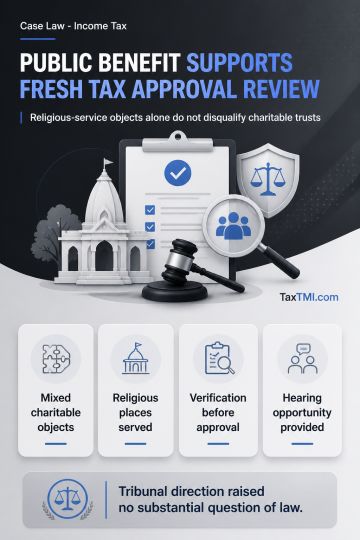
Section 13(1)(b)'s restriction on trusts benefiting a particular religious community applies when exemption under section 11 is considered, rather than at the section 12A registration stage. A trust whose objects are largely charitable and directed to the public at large is not disqualified merely because its objects include services to pilgrims and religious places. Where the trust is not established wholly for a particular religious community, its application for approval under section 80G(5) requires fresh consideration after verification and an opportunity of hearing. No substantial question of law arose from the Tribunal's direction for such reconsideration.
Section 13(1)(b)'s restriction on trusts benefiting a particular religious community applies when exemption under section 11 is considered, rather than at the section 12A registration stage. A trust whose objects are largely charitable and directed to the public at large is not disqualified merely because its objects include services to pilgrims and religious places. Where the trust is not established wholly for a particular religious community, its application for approval under section 80G(5) requires fresh consideration after verification and an opportunity of hearing. No substantial question of law arose from the Tribunal's direction for such reconsideration.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918