Social forestry expenditure requires activity-based classification, limiting book-profit adjustments and preserving penalty relief where normal additi...
Inaccurate-particulars penalties fail where transfer-pricing documentation shows good faith and due diligence, and underlying capital-gains additions ...
Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
Page of 4915
Press 'Enter' after typing page number.
1261 to 1280 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
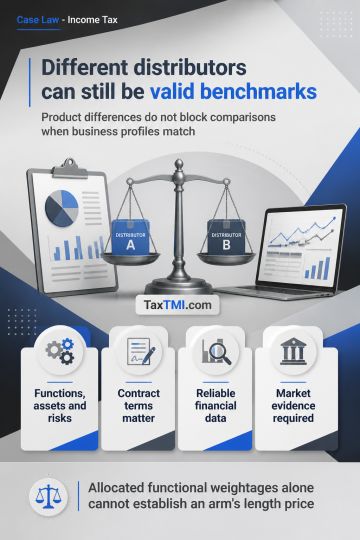
Functional comparability under TNMM for licence fees paid by a limited-risk distributor of licensed film and television content turns on functions, assets, risks, contractual terms and reliable financial data, rather than product similarity alone. Software and hardware distributors may therefore be valid comparables despite distributing different products. A revenue split under the Other Method requires comparable uncontrolled transactions, reliable market evidence or another objective economic basis to quantify contributions; allocated functional weightages alone cannot establish an arm's length price.
Functional comparability under TNMM for licence fees paid by a limited-risk distributor of licensed film and television content turns on functions, assets, risks, contractual terms and reliable financial data, rather than product similarity alone. Software and hardware distributors may therefore be valid comparables despite distributing different products. A revenue split under the Other Method requires comparable uncontrolled transactions, reliable market evidence or another objective economic basis to quantify contributions; allocated functional weightages alone cannot establish an arm's length price.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915