Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
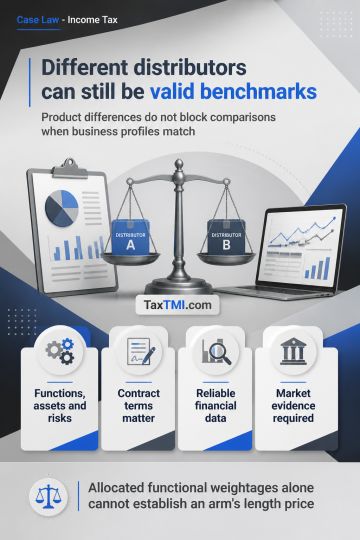
Functional comparability under TNMM for licence fees paid by a limited-risk distributor of licensed film and television content turns on functions, assets, risks, contractual terms and reliable financial data, rather than product similarity alone. Software and hardware distributors may therefore be valid comparables despite distributing different products. A revenue split under the Other Method requires comparable uncontrolled transactions, reliable market evidence or another objective economic basis to quantify contributions; allocated functional weightages alone cannot establish an arm's length price.
Functional comparability under TNMM for licence fees paid by a limited-risk distributor of licensed film and television content turns on functions, assets, risks, contractual terms and reliable financial data, rather than product similarity alone. Software and hardware distributors may therefore be valid comparables despite distributing different products. A revenue split under the Other Method requires comparable uncontrolled transactions, reliable market evidence or another objective economic basis to quantify contributions; allocated functional weightages alone cannot establish an arm's length price.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915