Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
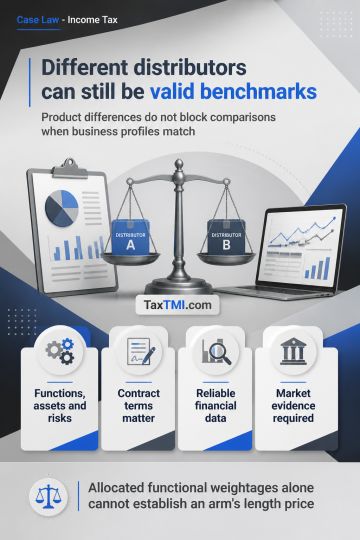
Functional comparability under TNMM for licence fees paid by a limited-risk distributor of licensed film and television content turns on functions, assets, risks, contractual terms and reliable financial data, rather than product similarity alone. Software and hardware distributors may therefore be valid comparables despite distributing different products. A revenue split under the Other Method requires comparable uncontrolled transactions, reliable market evidence or another objective economic basis to quantify contributions; allocated functional weightages alone cannot establish an arm's length price.
Functional comparability under TNMM for licence fees paid by a limited-risk distributor of licensed film and television content turns on functions, assets, risks, contractual terms and reliable financial data, rather than product similarity alone. Software and hardware distributors may therefore be valid comparables despite distributing different products. A revenue split under the Other Method requires comparable uncontrolled transactions, reliable market evidence or another objective economic basis to quantify contributions; allocated functional weightages alone cannot establish an arm's length price.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI