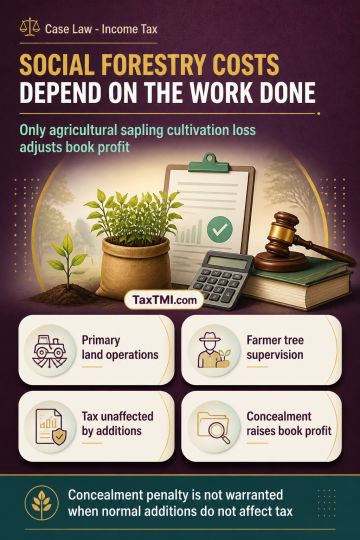
Social forestry expenditure requires activity-based classification, limiting book-profit adjustments and preserving penalty relief where normal additi...
Inaccurate-particulars penalties fail where transfer-pricing documentation shows good faith and due diligence, and underlying capital-gains additions ...
Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
Page of 4915
Press 'Enter' after typing page number.
1261 to 1280 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
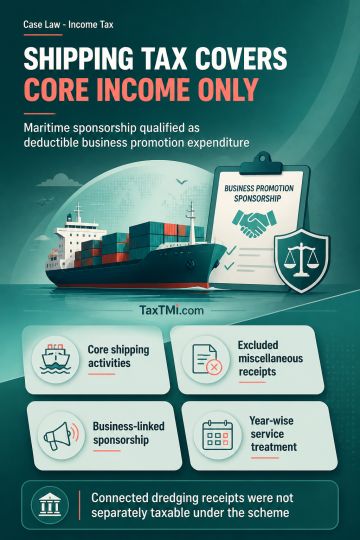
The Tonnage Tax Scheme confines relevant shipping income to profits from specified core and prescribed incidental shipping activities. Receipts from tender-document sales, contractor-delay damages, leased quarters, training fees, other operating income, and salary recoveries from resigned employees fell outside that scope, whereas scrap and empties sales, exchange differences, waste-oil sales, insurance claims, and provision reversals were treated as connected with dredging operations or not separately taxable. Service charges received differing treatment across assessment years in line with earlier determinations. Sponsorship for a maritime investment event qualified as business promotion expenditure because it had a direct business nexus and met commercial expediency, notwithstanding its accounting classification as donation; under the scheme, its debit or disallowance did not affect taxable-profit computation.
The Tonnage Tax Scheme confines relevant shipping income to profits from specified core and prescribed incidental shipping activities. Receipts from tender-document sales, contractor-delay damages, leased quarters, training fees, other operating income, and salary recoveries from resigned employees fell outside that scope, whereas scrap and empties sales, exchange differences, waste-oil sales, insurance claims, and provision reversals were treated as connected with dredging operations or not separately taxable. Service charges received differing treatment across assessment years in line with earlier determinations. Sponsorship for a maritime investment event qualified as business promotion expenditure because it had a direct business nexus and met commercial expediency, notwithstanding its accounting classification as donation; under the scheme, its debit or disallowance did not affect taxable-profit computation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915