E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
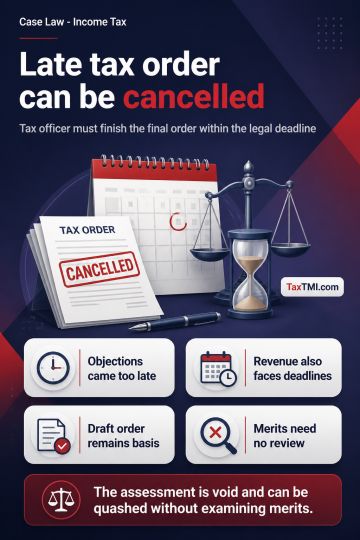
Time-barred DRP objections leave no valid objections for consideration. The AO must complete the assessment under section 144C(4)(b) on the basis of the draft order within the prescribed period and cannot await the DRP's disposal of belated objections. Statutory limitation binds both the assessee and the Revenue. A final assessment issued after that period because of such delay is barred by limitation, void ab initio, and liable to be quashed; merits need not be considered.
Time-barred DRP objections leave no valid objections for consideration. The AO must complete the assessment under section 144C(4)(b) on the basis of the draft order within the prescribed period and cannot await the DRP's disposal of belated objections. Statutory limitation binds both the assessee and the Revenue. A final assessment issued after that period because of such delay is barred by limitation, void ab initio, and liable to be quashed; merits need not be considered.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915