Turnover mismatches under percentage-completion accounting cannot alone establish suppressed income where customer advances remain recorded as liabili...
Territorial jurisdiction for money-laundering trials is revised for specified districts, replacing earlier court-area entries under the statutory fram...
Page of 4915
Press 'Enter' after typing page number.
1241 to 1260 of 98300 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
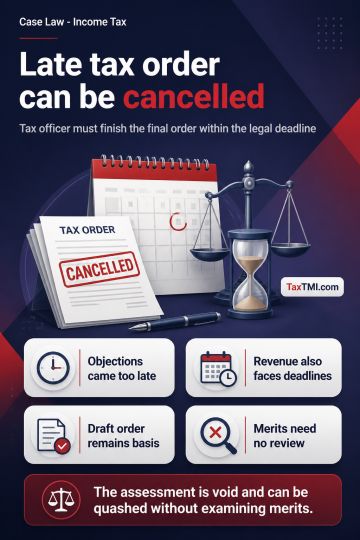
Time-barred DRP objections leave no valid objections for consideration. The AO must complete the assessment under section 144C(4)(b) on the basis of the draft order within the prescribed period and cannot await the DRP's disposal of belated objections. Statutory limitation binds both the assessee and the Revenue. A final assessment issued after that period because of such delay is barred by limitation, void ab initio, and liable to be quashed; merits need not be considered.
Time-barred DRP objections leave no valid objections for consideration. The AO must complete the assessment under section 144C(4)(b) on the basis of the draft order within the prescribed period and cannot await the DRP's disposal of belated objections. Statutory limitation binds both the assessee and the Revenue. A final assessment issued after that period because of such delay is barred by limitation, void ab initio, and liable to be quashed; merits need not be considered.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915