Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
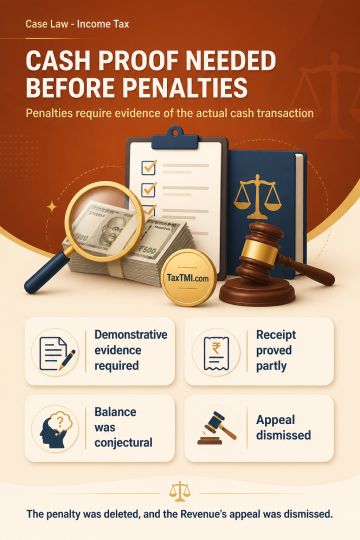
Penalty for alleged cash receipt cannot be imposed without demonstrative evidence establishing the actual cash transaction required for the cash-receipt restriction. Material showed a cash receipt only to a limited extent, while the balance was inferred conjecturally. Because the Revenue did not establish the factual basis for invoking section 269SS, deletion of the section 271D penalty was confirmed and its appeal dismissed.
Penalty for alleged cash receipt cannot be imposed without demonstrative evidence establishing the actual cash transaction required for the cash-receipt restriction. Material showed a cash receipt only to a limited extent, while the balance was inferred conjecturally. Because the Revenue did not establish the factual basis for invoking section 269SS, deletion of the section 271D penalty was confirmed and its appeal dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915