Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
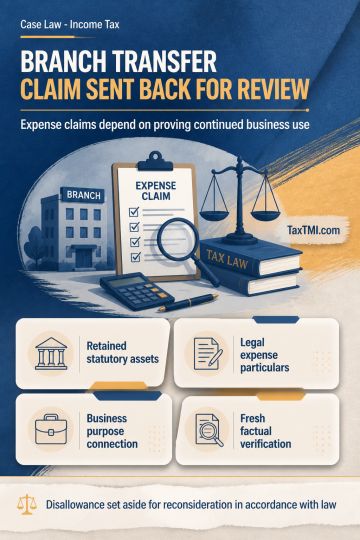
Business-expenditure deductibility after transfer of a branch undertaking depends on whether retained statutory assets and related expenditure continued to serve the business. The phrase "for the purpose of business" extends to acts incidental to carrying on business, but substantial legal and professional expenses cannot be allowed without complete particulars on their nature, purpose, and connection with business operations. Where those facts have not been examined, the disallowance requires fresh factual verification. The expenditure claim was remitted for de novo assessment, with the disallowance set aside for reconsideration in accordance with law.
Business-expenditure deductibility after transfer of a branch undertaking depends on whether retained statutory assets and related expenditure continued to serve the business. The phrase "for the purpose of business" extends to acts incidental to carrying on business, but substantial legal and professional expenses cannot be allowed without complete particulars on their nature, purpose, and connection with business operations. Where those facts have not been examined, the disallowance requires fresh factual verification. The expenditure claim was remitted for de novo assessment, with the disallowance set aside for reconsideration in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915