Concurrent anticipatory-bail jurisdiction permits applications before either forum, while secured evidence may negate custodial interrogation in GST e...
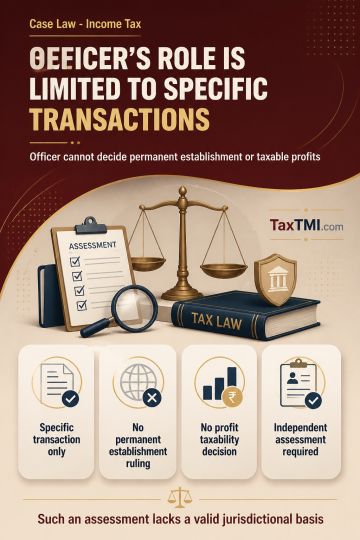
Transfer Pricing Officer jurisdiction is transaction-specific, excluding permanent establishment determinations and requiring independent assessment o...
Page of 4913
Press 'Enter' after typing page number.
1261 to 1280 of 98250 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
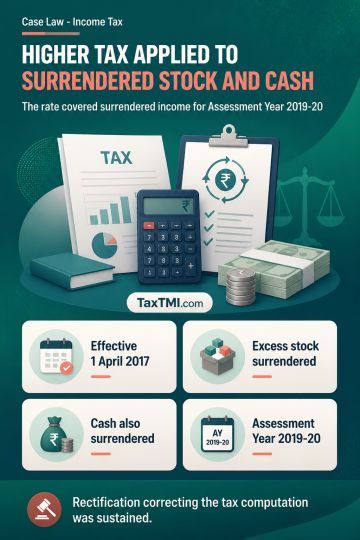
The enhanced tax rate under section 115BBE, operative from 1 April 2017, applies prospectively and therefore covers surrendered income from excess stock and cash for Assessment Year 2019-20. As the amended provision was already in force for that year, surrendered income was taxable at the enhanced rate. Rectification under section 154 to correct the tax computation was sustained.
Note: It is a system-generated summary and is for quick reference only.