Request-driven road restoration attracts reverse-charge GST, not governmental-function treatment or compensatory-damages status for business recipient...
Road restoration charges for commercial pipeline works are taxable Government services, with reverse charge liability and no public-function exemption...
Model-wise import cap monitoring cannot justify withholding used multifunction machines where all-India tracking is absent and full security is furnis...
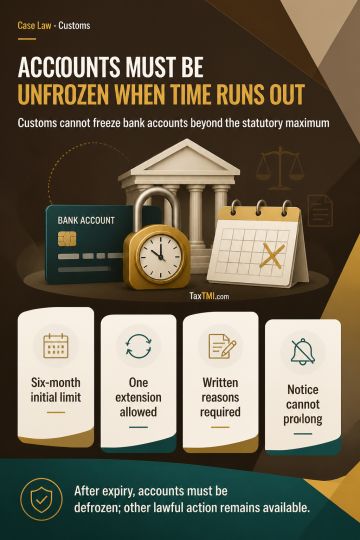
Section 110(5) of the Customs Act limits provisional attachment of a bank account to six months, with only one further extension of up to six months based on written reasons communicated before the original period expires. A show-cause notice or pending adjudication cannot independently prolong attachment beyond that statutory maximum. Once the period ends, the attachment ceases by efflux of time and cannot be continued through administrative action. Continued freezing without statutory authority requires defreezing of the account, without limiting any other action permitted by law.
Section 110(5) of the Customs Act limits provisional attachment of a bank account to six months, with only one further extension of up to six months based on written reasons communicated before the original period expires. A show-cause notice or pending adjudication cannot independently prolong attachment beyond that statutory maximum. Once the period ends, the attachment ceases by efflux of time and cannot be continued through administrative action. Continued freezing without statutory authority requires defreezing of the account, without limiting any other action permitted by law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915