Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
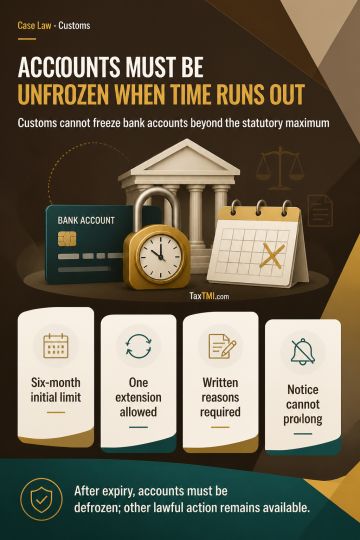
Section 110(5) of the Customs Act limits provisional attachment of a bank account to six months, with only one further extension of up to six months based on written reasons communicated before the original period expires. A show-cause notice or pending adjudication cannot independently prolong attachment beyond that statutory maximum. Once the period ends, the attachment ceases by efflux of time and cannot be continued through administrative action. Continued freezing without statutory authority requires defreezing of the account, without limiting any other action permitted by law.
Section 110(5) of the Customs Act limits provisional attachment of a bank account to six months, with only one further extension of up to six months based on written reasons communicated before the original period expires. A show-cause notice or pending adjudication cannot independently prolong attachment beyond that statutory maximum. Once the period ends, the attachment ceases by efflux of time and cannot be continued through administrative action. Continued freezing without statutory authority requires defreezing of the account, without limiting any other action permitted by law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915