Customs Assessment Portal centralises classification and valuation guidance to support consistent, transparent and informed compliance across stakehol...
GST refunds for cancelled air tickets remain available when passenger reimbursements defeat unjust enrichment and credit-note adjustment is unavailabl...
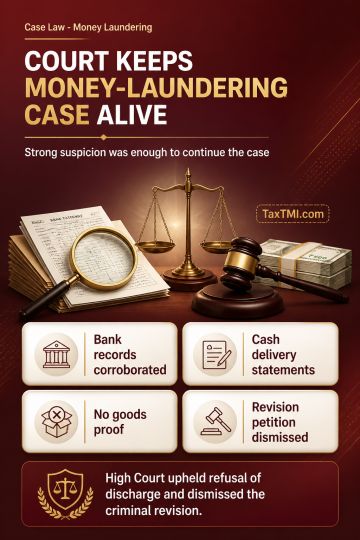
Discharge-stage scrutiny in a money-laundering prosecution is confined to whether the available material creates a strong suspicion reasonably connecting the accused with the alleged offence; it does not permit a roving enquiry or trial-level weighing of evidence. Statements indicating that funds were arranged and delivered at a co-accused's request, rather than through ordinary business, together with the absence of contemporaneous proof of goods supplied, supported the allegation. Bank records and statements from persons involved in arranging and delivering cash provided prima facie corroboration that the accused knowingly assisted a process connected with proceeds of crime. The High Court upheld refusal of discharge and dismissed the criminal revision.
Discharge-stage scrutiny in a money-laundering prosecution is confined to whether the available material creates a strong suspicion reasonably connecting the accused with the alleged offence; it does not permit a roving enquiry or trial-level weighing of evidence. Statements indicating that funds were arranged and delivered at a co-accused's request, rather than through ordinary business, together with the absence of contemporaneous proof of goods supplied, supported the allegation. Bank records and statements from persons involved in arranging and delivering cash provided prima facie corroboration that the accused knowingly assisted a process connected with proceeds of crime. The High Court upheld refusal of discharge and dismissed the criminal revision.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915