Turnover mismatches under percentage-completion accounting cannot alone establish suppressed income where customer advances remain recorded as liabili...
Territorial jurisdiction for money-laundering trials is revised for specified districts, replacing earlier court-area entries under the statutory fram...
Page of 4915
Press 'Enter' after typing page number.
1241 to 1260 of 98300 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
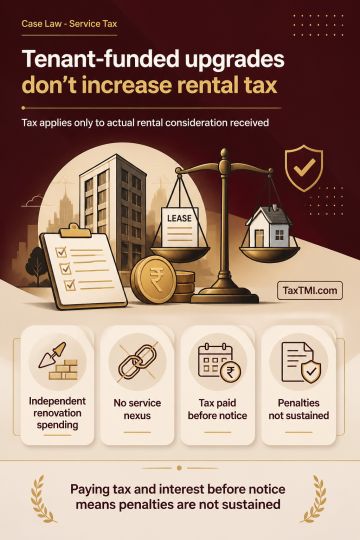
Recipient-funded renovation and development expenditure is excluded from the taxable value of renting of immovable property where it is incurred independently, is neither routed through nor controlled by the service provider, and lacks a nexus with the renting service. Service tax remains payable only on the actual rental consideration received. Where tax on that actual consideration and applicable interest are paid before issuance of a show-cause notice, penalties for failure to self-assess and for suppression under sections 77(2) and 78 of the Finance Act, 1994 are not sustained.
Recipient-funded renovation and development expenditure is excluded from the taxable value of renting of immovable property where it is incurred independently, is neither routed through nor controlled by the service provider, and lacks a nexus with the renting service. Service tax remains payable only on the actual rental consideration received. Where tax on that actual consideration and applicable interest are paid before issuance of a show-cause notice, penalties for failure to self-assess and for suppression under sections 77(2) and 78 of the Finance Act, 1994 are not sustained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915