Transfer-pricing comparability requires functional alignment; delayed associated-enterprise receivables need separate LIBOR-based benchmarking, while ...
Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
Customs transaction value rejection requires communicated reasonable doubt, while written reassessment acceptance preserves challenges to enhanced val...
Challenge-mechanism compliance clarifications permitted, while unilateral revised resolution plans may be refused under creditors' commercial discreti...
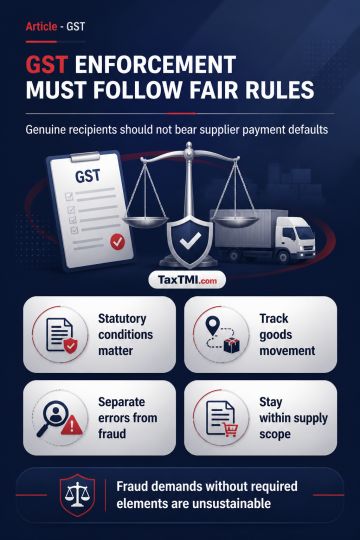
GST enforcement must adhere to statutory conditions, constitutional fairness and the rule of law rather than revenue targets. Input tax credit requires a reliable evidentiary trail establishing actual physical movement of goods, while bona fide purchasers and genuine recipients should not bear the consequences of a supplier's tax-payment default. Demand proceedings for fraud or wilful suppression require the essential statutory elements; absent those elements, such proceedings are unsustainable. Tax demands must also remain within the statutory scope of supply. A valid levy requires certainty regarding the taxable event, person liable, rate and measure of tax; ambiguity in any of these elements defeats the levy. Administrative authorities should address bona fide compliance errors proportionately and act as faithful trustees of statutory integrity.
GST enforcement must adhere to statutory conditions, constitutional fairness and the rule of law rather than revenue targets. Input tax credit requires a reliable evidentiary trail establishing actual physical movement of goods, while bona fide purchasers and genuine recipients should not bear the consequences of a supplier's tax-payment default. Demand proceedings for fraud or wilful suppression require the essential statutory elements; absent those elements, such proceedings are unsustainable. Tax demands must also remain within the statutory scope of supply. A valid levy requires certainty regarding the taxable event, person liable, rate and measure of tax; ambiguity in any of these elements defeats the levy. Administrative authorities should address bona fide compliance errors proportionately and act as faithful trustees of statutory integrity.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916