Transfer-pricing comparability requires functional alignment; delayed associated-enterprise receivables need separate LIBOR-based benchmarking, while ...
Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
Customs transaction value rejection requires communicated reasonable doubt, while written reassessment acceptance preserves challenges to enhanced val...
Challenge-mechanism compliance clarifications permitted, while unilateral revised resolution plans may be refused under creditors' commercial discreti...
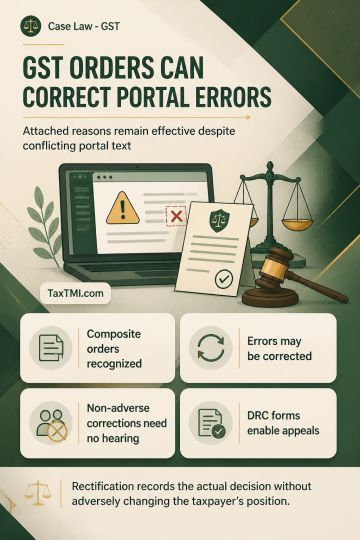
GST adjudication orders that expressly incorporate annexures must be read as composite instruments. A digitally signed portal-generated order can validly authenticate an accompanying annexure containing the reasons, input tax credit determination and consequential liability; an inconsistent portal recital that proceedings were dropped does not sever or invalidate the incorporated annexure. Rectification may correct an error apparent from the record to reflect the decision actually made, but cannot reopen merits or create a fresh adjudication. No further hearing is required where the correction does not adversely alter the taxpayer's original position. FORM GST DRC-07 is a statutory summary rather than the adjudication itself, but DRC-07 and corresponding DRC-08 must be made available within a reasonable time to permit appeal and demand enforcement.
GST adjudication orders that expressly incorporate annexures must be read as composite instruments. A digitally signed portal-generated order can validly authenticate an accompanying annexure containing the reasons, input tax credit determination and consequential liability; an inconsistent portal recital that proceedings were dropped does not sever or invalidate the incorporated annexure. Rectification may correct an error apparent from the record to reflect the decision actually made, but cannot reopen merits or create a fresh adjudication. No further hearing is required where the correction does not adversely alter the taxpayer's original position. FORM GST DRC-07 is a statutory summary rather than the adjudication itself, but DRC-07 and corresponding DRC-08 must be made available within a reasonable time to permit appeal and demand enforcement.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916