Electronic certificates of origin enable preferential tariffs under the India-New Zealand FTA when format, verification, and filing requirements are m...
Customs approval for liquid cargo exports extends designated jetty operations while existing boarding station and customs area limits remain unchanged...
Mandatory compliance document verification now conditions out-of-charge clearance for imported cosmetics, drugs, and medical devices through PGA-facil...
Page of 4921
Press 'Enter' after typing page number.
1 to 20 of 98414 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
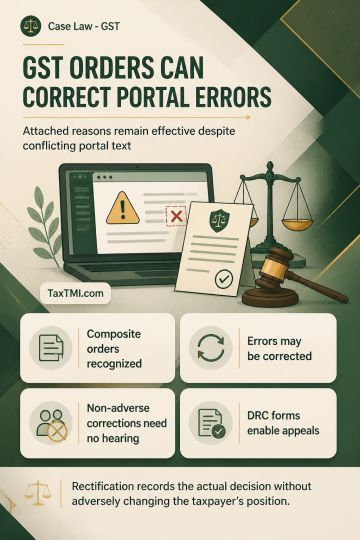
GST adjudication orders that expressly incorporate annexures must be read as composite instruments. A digitally signed portal-generated order can validly authenticate an accompanying annexure containing the reasons, input tax credit determination and consequential liability; an inconsistent portal recital that proceedings were dropped does not sever or invalidate the incorporated annexure. Rectification may correct an error apparent from the record to reflect the decision actually made, but cannot reopen merits or create a fresh adjudication. No further hearing is required where the correction does not adversely alter the taxpayer's original position. FORM GST DRC-07 is a statutory summary rather than the adjudication itself, but DRC-07 and corresponding DRC-08 must be made available within a reasonable time to permit appeal and demand enforcement.
GST adjudication orders that expressly incorporate annexures must be read as composite instruments. A digitally signed portal-generated order can validly authenticate an accompanying annexure containing the reasons, input tax credit determination and consequential liability; an inconsistent portal recital that proceedings were dropped does not sever or invalidate the incorporated annexure. Rectification may correct an error apparent from the record to reflect the decision actually made, but cannot reopen merits or create a fresh adjudication. No further hearing is required where the correction does not adversely alter the taxpayer's original position. FORM GST DRC-07 is a statutory summary rather than the adjudication itself, but DRC-07 and corresponding DRC-08 must be made available within a reasonable time to permit appeal and demand enforcement.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI