Customs Broker due diligence requires prescribed KYC, not detecting misdeclarations discoverable only through physical examination, defeating licence ...
E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
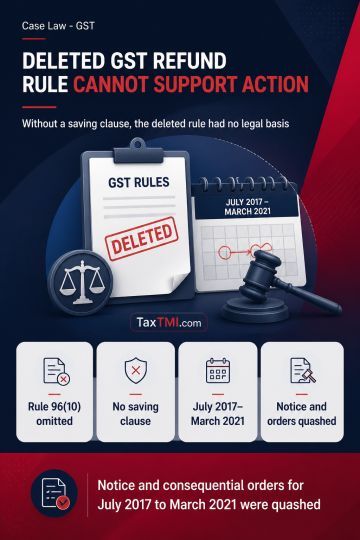
Unconditional omission of Rule 96(10) of the CGST/WBGST Rules, 2017, without a saving clause, rendered the rule nonexistent for proceedings founded solely on it. Applying Supreme Court law on the effect of such omission, the High Court found that the impugned proceedings had no independent statutory basis. The show-cause notice and consequential orders concerning July 2017 to March 2021 were therefore quashed, and the writ petition was disposed of.
Unconditional omission of Rule 96(10) of the CGST/WBGST Rules, 2017, without a saving clause, rendered the rule nonexistent for proceedings founded solely on it. Applying Supreme Court law on the effect of such omission, the High Court found that the impugned proceedings had no independent statutory basis. The show-cause notice and consequential orders concerning July 2017 to March 2021 were therefore quashed, and the writ petition was disposed of.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915