Request-driven road restoration attracts reverse-charge GST, not governmental-function treatment or compensatory-damages status for business recipient...
Road restoration charges for commercial pipeline works are taxable Government services, with reverse charge liability and no public-function exemption...
Model-wise import cap monitoring cannot justify withholding used multifunction machines where all-India tracking is absent and full security is furnis...
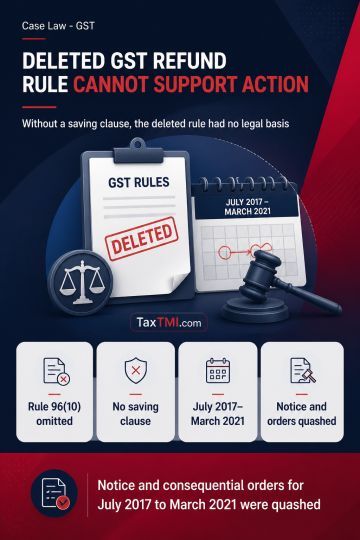
Unconditional omission of Rule 96(10) of the CGST/WBGST Rules, 2017, without a saving clause, rendered the rule nonexistent for proceedings founded solely on it. Applying Supreme Court law on the effect of such omission, the High Court found that the impugned proceedings had no independent statutory basis. The show-cause notice and consequential orders concerning July 2017 to March 2021 were therefore quashed, and the writ petition was disposed of.
Unconditional omission of Rule 96(10) of the CGST/WBGST Rules, 2017, without a saving clause, rendered the rule nonexistent for proceedings founded solely on it. Applying Supreme Court law on the effect of such omission, the High Court found that the impugned proceedings had no independent statutory basis. The show-cause notice and consequential orders concerning July 2017 to March 2021 were therefore quashed, and the writ petition was disposed of.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915