Request-driven road restoration attracts reverse-charge GST, not governmental-function treatment or compensatory-damages status for business recipient...
Road restoration charges for commercial pipeline works are taxable Government services, with reverse charge liability and no public-function exemption...
Model-wise import cap monitoring cannot justify withholding used multifunction machines where all-India tracking is absent and full security is furnis...
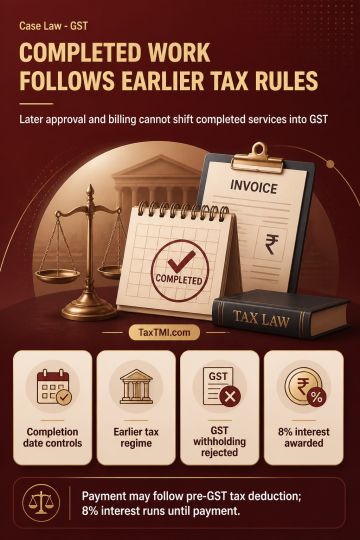
Services rendered and completed before the GST appointed day remain subject, if taxable, to the erstwhile Service Tax regime even where work approval and billing occur after GST commenced. Post-facto approval and subsequent invoices do not alter the date of supply or bring an already completed manpower service within the WBGST Act. Payment cannot be withheld solely for non-compliance with GST formalities; the payable amount may be released after deduction of applicable pre-GST tax. Where a genuine taxability dispute and pending civil proceedings contribute to delayed payment, interest may be set at the prevailing banking rate; interest at 8% per annum was directed from bill submission until payment.
Services rendered and completed before the GST appointed day remain subject, if taxable, to the erstwhile Service Tax regime even where work approval and billing occur after GST commenced. Post-facto approval and subsequent invoices do not alter the date of supply or bring an already completed manpower service within the WBGST Act. Payment cannot be withheld solely for non-compliance with GST formalities; the payable amount may be released after deduction of applicable pre-GST tax. Where a genuine taxability dispute and pending civil proceedings contribute to delayed payment, interest may be set at the prevailing banking rate; interest at 8% per annum was directed from bill submission until payment.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918