Stamp valuation increases after registration-fee payment led to deletion of property-purchase addition within tolerance and without valuation referral...
Capital Asset Conversion Requires Proven Business Stock Treatment; Paper Consideration in Spousal Flat Transfers Does Not Create Taxable Business Inco...
Human-probability test defeats political donation deduction where banking records mask accommodation-entry fund layering and evidence shows non-genuin...
Page of 4925
Press 'Enter' after typing page number.
1221 to 1240 of 98494 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
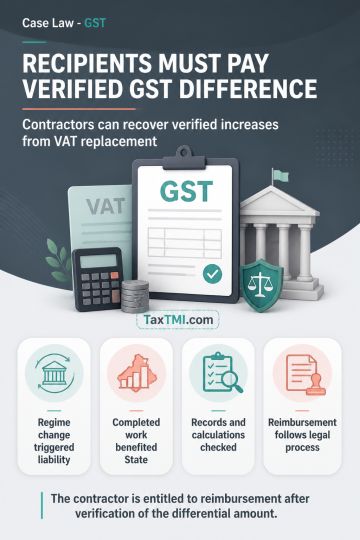
Differential GST arising from the replacement of VAT by GST during an ongoing works contract is to be borne by the recipient of the works contract service. Where the contractor has discharged that additional liability and the State has received the benefit of the completed work, the contractor is entitled to reimbursement of the verified differential amount. High Court directed the respondents to determine the GST differential attributable to the tax-regime change, verify the relevant records and calculations, and reimburse the amount in accordance with law within the stipulated period.
Differential GST arising from the replacement of VAT by GST during an ongoing works contract is to be borne by the recipient of the works contract service. Where the contractor has discharged that additional liability and the State has received the benefit of the completed work, the contractor is entitled to reimbursement of the verified differential amount. High Court directed the respondents to determine the GST differential attributable to the tax-regime change, verify the relevant records and calculations, and reimburse the amount in accordance with law within the stipulated period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4925