Request-driven road restoration attracts reverse-charge GST, not governmental-function treatment or compensatory-damages status for business recipient...
Road restoration charges for commercial pipeline works are taxable Government services, with reverse charge liability and no public-function exemption...
Model-wise import cap monitoring cannot justify withholding used multifunction machines where all-India tracking is absent and full security is furnis...
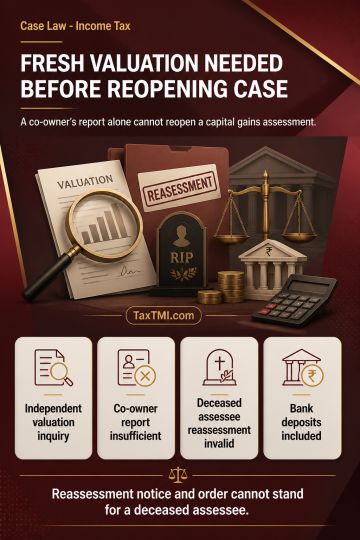
Reassessment initiated in the name of a deceased assessee is invalid, and the resulting notice and order cannot be sustained where section 159(2)(b) applies. For extended reassessment limitation, capital gains from land may constitute income represented in the form of an asset when the sale proceeds are deposited in a bank account, because bank deposits fall within the inclusive statutory explanation. Reassessment for alleged understatement of capital gains cannot rest solely on a co-owner's valuation report. The Assessing Officer must undertake an appropriate independent valuation inquiry, examine valuation methodology, apply independent mind, and form the required belief of income escaping assessment.
Reassessment initiated in the name of a deceased assessee is invalid, and the resulting notice and order cannot be sustained where section 159(2)(b) applies. For extended reassessment limitation, capital gains from land may constitute income represented in the form of an asset when the sale proceeds are deposited in a bank account, because bank deposits fall within the inclusive statutory explanation. Reassessment for alleged understatement of capital gains cannot rest solely on a co-owner's valuation report. The Assessing Officer must undertake an appropriate independent valuation inquiry, examine valuation methodology, apply independent mind, and form the required belief of income escaping assessment.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915