Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
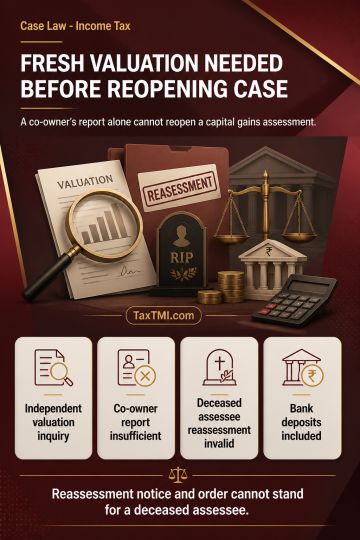
Reassessment initiated in the name of a deceased assessee is invalid, and the resulting notice and order cannot be sustained where section 159(2)(b) applies. For extended reassessment limitation, capital gains from land may constitute income represented in the form of an asset when the sale proceeds are deposited in a bank account, because bank deposits fall within the inclusive statutory explanation. Reassessment for alleged understatement of capital gains cannot rest solely on a co-owner's valuation report. The Assessing Officer must undertake an appropriate independent valuation inquiry, examine valuation methodology, apply independent mind, and form the required belief of income escaping assessment.
Reassessment initiated in the name of a deceased assessee is invalid, and the resulting notice and order cannot be sustained where section 159(2)(b) applies. For extended reassessment limitation, capital gains from land may constitute income represented in the form of an asset when the sale proceeds are deposited in a bank account, because bank deposits fall within the inclusive statutory explanation. Reassessment for alleged understatement of capital gains cannot rest solely on a co-owner's valuation report. The Assessing Officer must undertake an appropriate independent valuation inquiry, examine valuation methodology, apply independent mind, and form the required belief of income escaping assessment.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915