Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
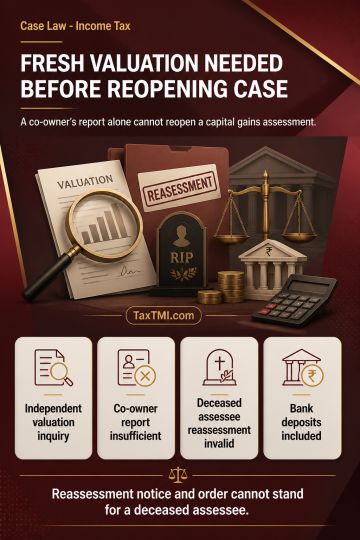
Reassessment initiated in the name of a deceased assessee is invalid, and the resulting notice and order cannot be sustained where section 159(2)(b) applies. For extended reassessment limitation, capital gains from land may constitute income represented in the form of an asset when the sale proceeds are deposited in a bank account, because bank deposits fall within the inclusive statutory explanation. Reassessment for alleged understatement of capital gains cannot rest solely on a co-owner's valuation report. The Assessing Officer must undertake an appropriate independent valuation inquiry, examine valuation methodology, apply independent mind, and form the required belief of income escaping assessment.
Reassessment initiated in the name of a deceased assessee is invalid, and the resulting notice and order cannot be sustained where section 159(2)(b) applies. For extended reassessment limitation, capital gains from land may constitute income represented in the form of an asset when the sale proceeds are deposited in a bank account, because bank deposits fall within the inclusive statutory explanation. Reassessment for alleged understatement of capital gains cannot rest solely on a co-owner's valuation report. The Assessing Officer must undertake an appropriate independent valuation inquiry, examine valuation methodology, apply independent mind, and form the required belief of income escaping assessment.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI