Section 153C requires person-specific search authority and year-specific incriminating material for unabated assessments while preventing unsupported ...
Equivalent-value attachment can reach pre-existing assets, but jointly owned property remains protected beyond the accused's attributable proceeds of ...
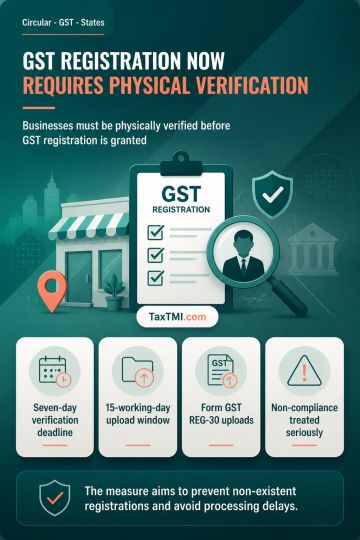
Pre-registration physical verification becomes mandatory to prevent non-existent business registrations and support timely GST registration processing...
Page of 4920
Press 'Enter' after typing page number.
1521 to 1540 of 98394 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
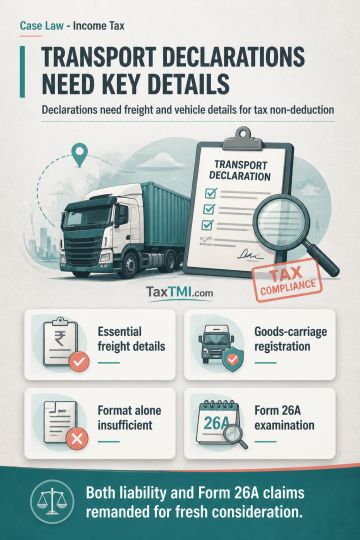
Declarations under section 194C(6) need not follow the CBDT circular format, but must contain essential freight-charge and goods-carriage registration particulars to establish eligibility for non-deduction of tax on payments to small transport operators. Declarations cannot be rejected solely for format non-compliance or lack of independent verification, although identified discrepancies or omissions must be put to the payer; the ITAT remanded the matter because transporter-specific deficiencies were not identified. Physical Form 26A certificates must also be examined under the first proviso to section 201(1) to determine whether payees included freight income in their returns and paid due tax. Assessee-in-default liability and the alternative Form 26A claim were remanded for fresh consideration.
Declarations under section 194C(6) need not follow the CBDT circular format, but must contain essential freight-charge and goods-carriage registration particulars to establish eligibility for non-deduction of tax on payments to small transport operators. Declarations cannot be rejected solely for format non-compliance or lack of independent verification, although identified discrepancies or omissions must be put to the payer; the ITAT remanded the matter because transporter-specific deficiencies were not identified. Physical Form 26A certificates must also be examined under the first proviso to section 201(1) to determine whether payees included freight income in their returns and paid due tax. Assessee-in-default liability and the alternative Form 26A claim were remanded for fresh consideration.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4920