Concurrent anticipatory-bail jurisdiction permits applications before either forum, while secured evidence may negate custodial interrogation in GST e...
Transfer Pricing Officer jurisdiction is transaction-specific, excluding permanent establishment determinations and requiring independent assessment o...
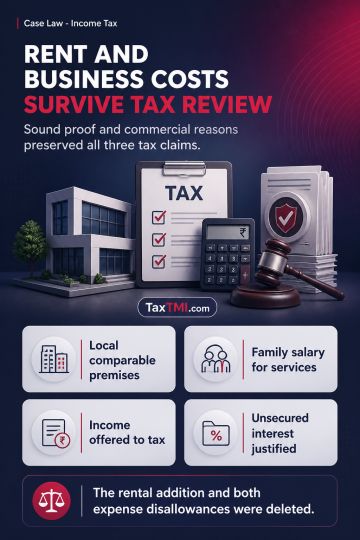
Rental income valuation requires credible local comparables; family-business salary and commercially expedient unsecured-loan interest remained deduct...
Reasonable cause under section 273B excused failures to deduct tax from rent paid to a Government-owned company and to collect tax on construction scrap. ITAT accepted the payer's bona fide belief that the Government-owned payee was a Government instrumentality not subject to tax deduction at source, treating that belief as reasonable cause; the rent-related penalty was deleted. ITAT also accepted the bona fide understanding that scrap arising from construction activities, including cutting and moulding materials, was not scrap covered by the tax-collection provisions because construction was not treated as manufacturing. The related tax-collection penalty was likewise deleted.
Reasonable cause under section 273B excused failures to deduct tax from rent paid to a Government-owned company and to collect tax on construction scrap. ITAT accepted the payer's bona fide belief that the Government-owned payee was a Government instrumentality not subject to tax deduction at source, treating that belief as reasonable cause; the rent-related penalty was deleted. ITAT also accepted the bona fide understanding that scrap arising from construction activities, including cutting and moulding materials, was not scrap covered by the tax-collection provisions because construction was not treated as manufacturing. The related tax-collection penalty was likewise deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915