Section 47-A undervaluation threshold: fraudulent intent requirement faces reconsideration after referral to a larger Bench for authoritative resoluti...
RBI supersession powers over multi-State co-operative banks operate independently of the constitutional six-month ceiling and permit statutory extensi...
Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Page of 4921
Press 'Enter' after typing page number.
1721 to 1740 of 98411 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
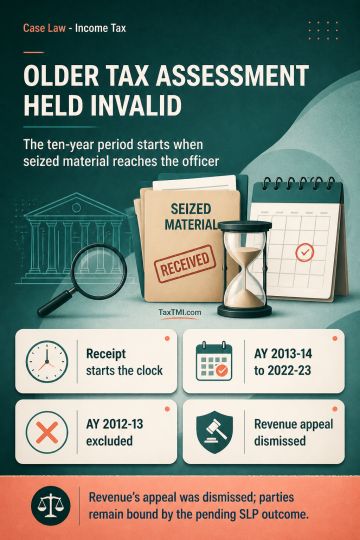
The first proviso to section 153C shifts the commencement of the six- and ten-year assessment block for a non-searched person from the search date to the date on which that person's jurisdictional Assessing Officer receives the seized material. Applying this legal fiction, satisfaction notes and notice issued in FY 2021-22 made AY 2022-23 the relevant year, limiting the ten-year block to AYs 2013-14 through 2022-23. AY 2012-13 therefore fell outside the permissible period, rendering its assessment invalid and resulting in dismissal of the Revenue's appeal. The parties remain bound by the outcome of the pending SLP concerning the governing precedent.
The first proviso to section 153C shifts the commencement of the six- and ten-year assessment block for a non-searched person from the search date to the date on which that person's jurisdictional Assessing Officer receives the seized material. Applying this legal fiction, satisfaction notes and notice issued in FY 2021-22 made AY 2022-23 the relevant year, limiting the ten-year block to AYs 2013-14 through 2022-23. AY 2012-13 therefore fell outside the permissible period, rendering its assessment invalid and resulting in dismissal of the Revenue's appeal. The parties remain bound by the outcome of the pending SLP concerning the governing precedent.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921