Transfer-pricing comparability requires functional alignment; delayed associated-enterprise receivables need separate LIBOR-based benchmarking, while ...
Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
Customs transaction value rejection requires communicated reasonable doubt, while written reassessment acceptance preserves challenges to enhanced val...
Challenge-mechanism compliance clarifications permitted, while unilateral revised resolution plans may be refused under creditors' commercial discreti...
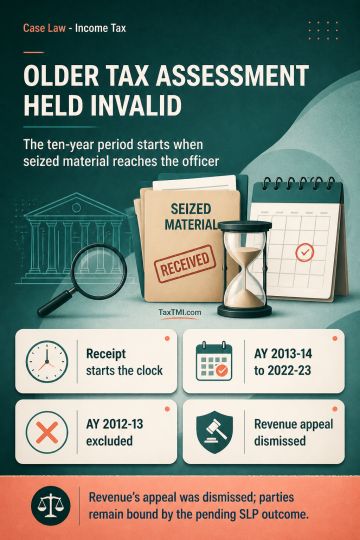
The first proviso to section 153C shifts the commencement of the six- and ten-year assessment block for a non-searched person from the search date to the date on which that person's jurisdictional Assessing Officer receives the seized material. Applying this legal fiction, satisfaction notes and notice issued in FY 2021-22 made AY 2022-23 the relevant year, limiting the ten-year block to AYs 2013-14 through 2022-23. AY 2012-13 therefore fell outside the permissible period, rendering its assessment invalid and resulting in dismissal of the Revenue's appeal. The parties remain bound by the outcome of the pending SLP concerning the governing precedent.
The first proviso to section 153C shifts the commencement of the six- and ten-year assessment block for a non-searched person from the search date to the date on which that person's jurisdictional Assessing Officer receives the seized material. Applying this legal fiction, satisfaction notes and notice issued in FY 2021-22 made AY 2022-23 the relevant year, limiting the ten-year block to AYs 2013-14 through 2022-23. AY 2012-13 therefore fell outside the permissible period, rendering its assessment invalid and resulting in dismissal of the Revenue's appeal. The parties remain bound by the outcome of the pending SLP concerning the governing precedent.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916