Request-driven road restoration attracts reverse-charge GST, not governmental-function treatment or compensatory-damages status for business recipient...
Road restoration charges for commercial pipeline works are taxable Government services, with reverse charge liability and no public-function exemption...
Model-wise import cap monitoring cannot justify withholding used multifunction machines where all-India tracking is absent and full security is furnis...
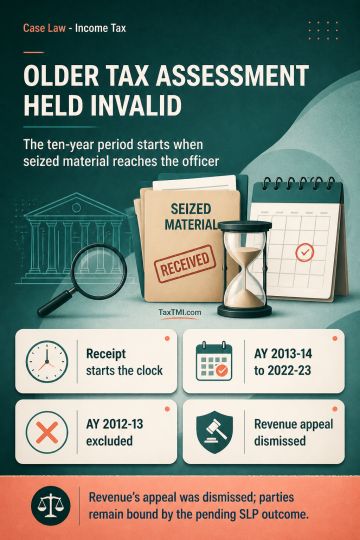
The first proviso to section 153C shifts the commencement of the six- and ten-year assessment block for a non-searched person from the search date to the date on which that person's jurisdictional Assessing Officer receives the seized material. Applying this legal fiction, satisfaction notes and notice issued in FY 2021-22 made AY 2022-23 the relevant year, limiting the ten-year block to AYs 2013-14 through 2022-23. AY 2012-13 therefore fell outside the permissible period, rendering its assessment invalid and resulting in dismissal of the Revenue's appeal. The parties remain bound by the outcome of the pending SLP concerning the governing precedent.
The first proviso to section 153C shifts the commencement of the six- and ten-year assessment block for a non-searched person from the search date to the date on which that person's jurisdictional Assessing Officer receives the seized material. Applying this legal fiction, satisfaction notes and notice issued in FY 2021-22 made AY 2022-23 the relevant year, limiting the ten-year block to AYs 2013-14 through 2022-23. AY 2012-13 therefore fell outside the permissible period, rendering its assessment invalid and resulting in dismissal of the Revenue's appeal. The parties remain bound by the outcome of the pending SLP concerning the governing precedent.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915