Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
Commodity derivatives position limits adopt revised breach penalties, broad commodity criteria, and client open-position limits based on deliverable s...
Page of 4916
Press 'Enter' after typing page number.
1501 to 1520 of 98302 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
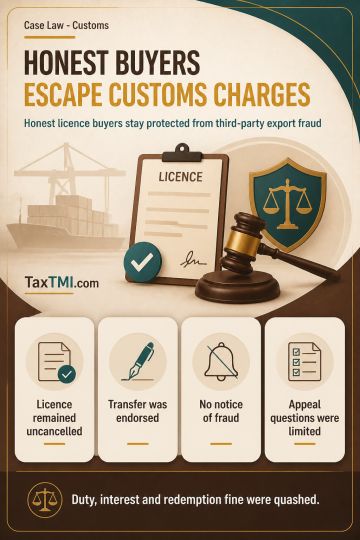
An uncancelled duty-free import licence obtained through fraud or misrepresentation remains voidable rather than void from inception. Where the licence was genuinely issued, endorsed transferable and not cancelled by the competent authority, a bona fide transferee for value without notice of third-party fraud in export-obligation certification is distinct from the fraudster and cannot be subjected to duty, interest or redemption fine for imports under that licence. The principle that fraud vitiates everything does not displace those rights in this setting. A statutory appeal confined to substantial questions framed at admission cannot be decided on an unframed limitation ground unless an additional question is formally permitted. The duty demand, interest and redemption fine were quashed.
An uncancelled duty-free import licence obtained through fraud or misrepresentation remains voidable rather than void from inception. Where the licence was genuinely issued, endorsed transferable and not cancelled by the competent authority, a bona fide transferee for value without notice of third-party fraud in export-obligation certification is distinct from the fraudster and cannot be subjected to duty, interest or redemption fine for imports under that licence. The principle that fraud vitiates everything does not displace those rights in this setting. A statutory appeal confined to substantial questions framed at admission cannot be decided on an unframed limitation ground unless an additional question is formally permitted. The duty demand, interest and redemption fine were quashed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916