Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
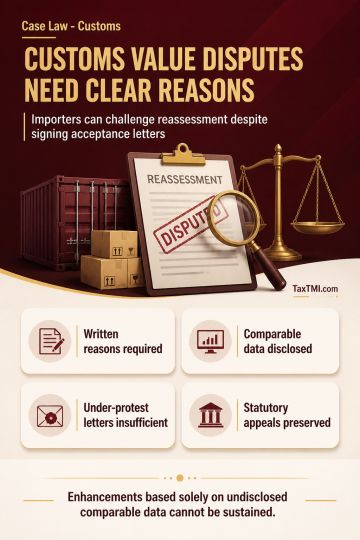
Customs valuation safeguards require the proper officer to communicate written reasons for doubting a declared transaction value and disclose relevant contemporaneous import particulars, including quantity, quality and temporal comparability. Acceptance letters given while seeking clearance on payment of duty under protest do not by themselves establish voluntary acceptance of enhanced value or waive these requirements. Written acceptance of reassessment may dispense with a speaking order, but it does not extinguish the statutory right to challenge reassessment on merits. Consent or acquiescence cannot defeat a statutory appeal; enhancement founded solely on undisclosed comparable data and acceptance letters cannot be sustained, and rejection of such appeals must be set aside with consequential relief.
Customs valuation safeguards require the proper officer to communicate written reasons for doubting a declared transaction value and disclose relevant contemporaneous import particulars, including quantity, quality and temporal comparability. Acceptance letters given while seeking clearance on payment of duty under protest do not by themselves establish voluntary acceptance of enhanced value or waive these requirements. Written acceptance of reassessment may dispense with a speaking order, but it does not extinguish the statutory right to challenge reassessment on merits. Consent or acquiescence cannot defeat a statutory appeal; enhancement founded solely on undisclosed comparable data and acceptance letters cannot be sustained, and rejection of such appeals must be set aside with consequential relief.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI