Business expenditure and depreciation rules allow operational outgoings while limiting disallowances for personal elements and unsupported third-party...
Compromise-and-arrangement extensions may accommodate debt assignment where creditor commercial judgment supports value maximisation and avoids proced...
Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution trea...
Sufficient cause for delayed revenue income-tax appeals requires bona fides, due diligence and a credible explanation; otherwise limitation bars appea...
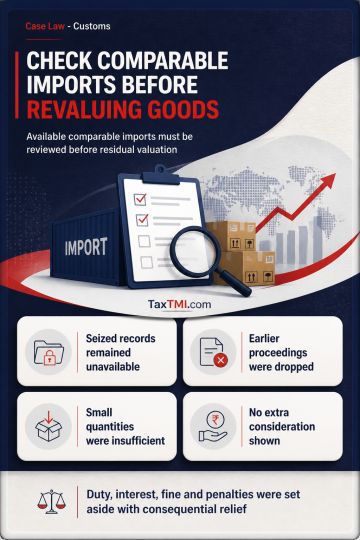
Departmental custody of seized laboratory registers, test reports and backup records precludes an adverse inference against an importer for not producing that material to classify fish meal as finished goods. Earlier examination of laboratory reports and BIS specifications had dropped proceedings concerning the same product. Customs valuation must follow the sequential framework: available contemporaneous comparable imports require identification, comparison and reasoned rejection before residual valuation may be used. Small quantities alone did not justify bypassing comparable-goods methods, and no evidence established consideration beyond invoice value. The classification and re-determined valuation were unsustainable, so the duty demand, interest, fine and penalties were set aside with consequential relief.
Departmental custody of seized laboratory registers, test reports and backup records precludes an adverse inference against an importer for not producing that material to classify fish meal as finished goods. Earlier examination of laboratory reports and BIS specifications had dropped proceedings concerning the same product. Customs valuation must follow the sequential framework: available contemporaneous comparable imports require identification, comparison and reasoned rejection before residual valuation may be used. Small quantities alone did not justify bypassing comparable-goods methods, and no evidence established consideration beyond invoice value. The classification and re-determined valuation were unsustainable, so the duty demand, interest, fine and penalties were set aside with consequential relief.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916