Turnover mismatches under percentage-completion accounting cannot alone establish suppressed income where customer advances remain recorded as liabili...
Territorial jurisdiction for money-laundering trials is revised for specified districts, replacing earlier court-area entries under the statutory fram...
Page of 4915
Press 'Enter' after typing page number.
1241 to 1260 of 98300 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
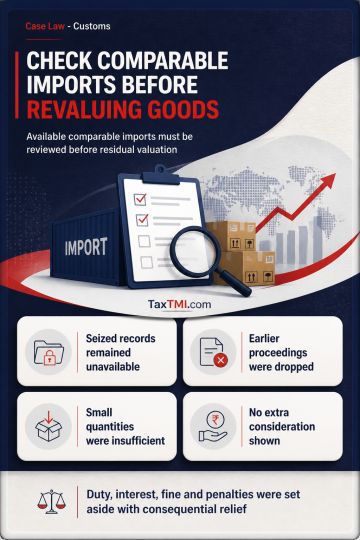
Departmental custody of seized laboratory registers, test reports and backup records precludes an adverse inference against an importer for not producing that material to classify fish meal as finished goods. Earlier examination of laboratory reports and BIS specifications had dropped proceedings concerning the same product. Customs valuation must follow the sequential framework: available contemporaneous comparable imports require identification, comparison and reasoned rejection before residual valuation may be used. Small quantities alone did not justify bypassing comparable-goods methods, and no evidence established consideration beyond invoice value. The classification and re-determined valuation were unsustainable, so the duty demand, interest, fine and penalties were set aside with consequential relief.
Departmental custody of seized laboratory registers, test reports and backup records precludes an adverse inference against an importer for not producing that material to classify fish meal as finished goods. Earlier examination of laboratory reports and BIS specifications had dropped proceedings concerning the same product. Customs valuation must follow the sequential framework: available contemporaneous comparable imports require identification, comparison and reasoned rejection before residual valuation may be used. Small quantities alone did not justify bypassing comparable-goods methods, and no evidence established consideration beyond invoice value. The classification and re-determined valuation were unsustainable, so the duty demand, interest, fine and penalties were set aside with consequential relief.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915